6.1 Target Asset Classes
| Asset Class | Markets (Illustrative) | Rationale |
|---|---|---|
| Grade A Office | Hong Kong, Singapore | Stable long-term tenancies; transparent rental benchmarks; institutional-grade liquidity on exit |
| Logistics / Industrial | Japan, Malaysia, Vietnam | Structural tailwind from e-commerce and nearshoring; long WALTs; low capex |
| Hospitality & Mixed-Use | Thailand, UAE, Bali | High yield potential; tourism recovery thesis; limited direct tokenization competition |
| Residential (Premium) | Hong Kong, Singapore | Capital value appreciation; robust rental demand from expatriate and HNWI communities |
| Development Projects (Select) | Vietnam, Indonesia, Philippines | Early-stage premium; higher risk-adjusted return; minority stake structures |
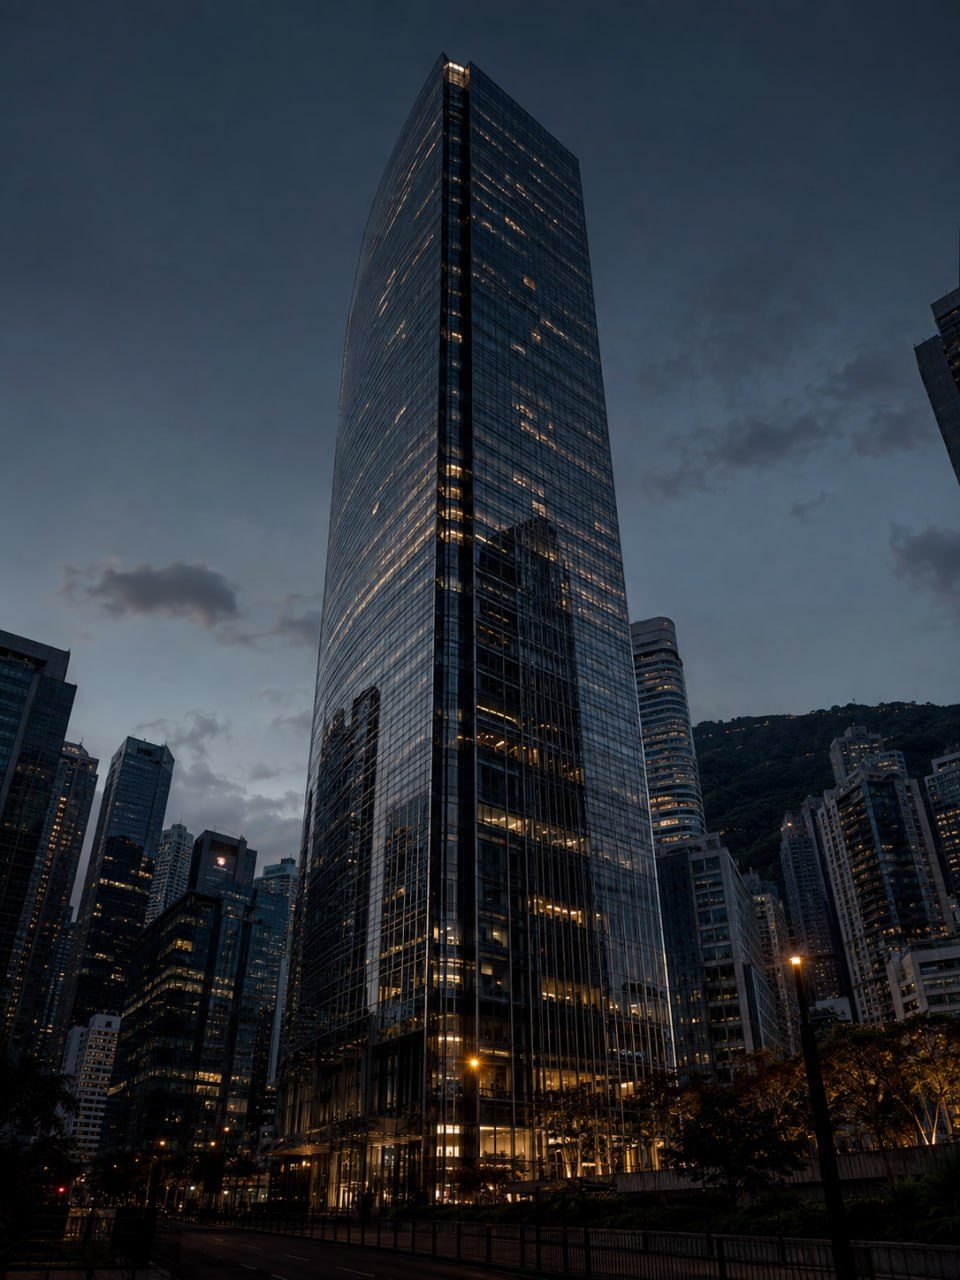
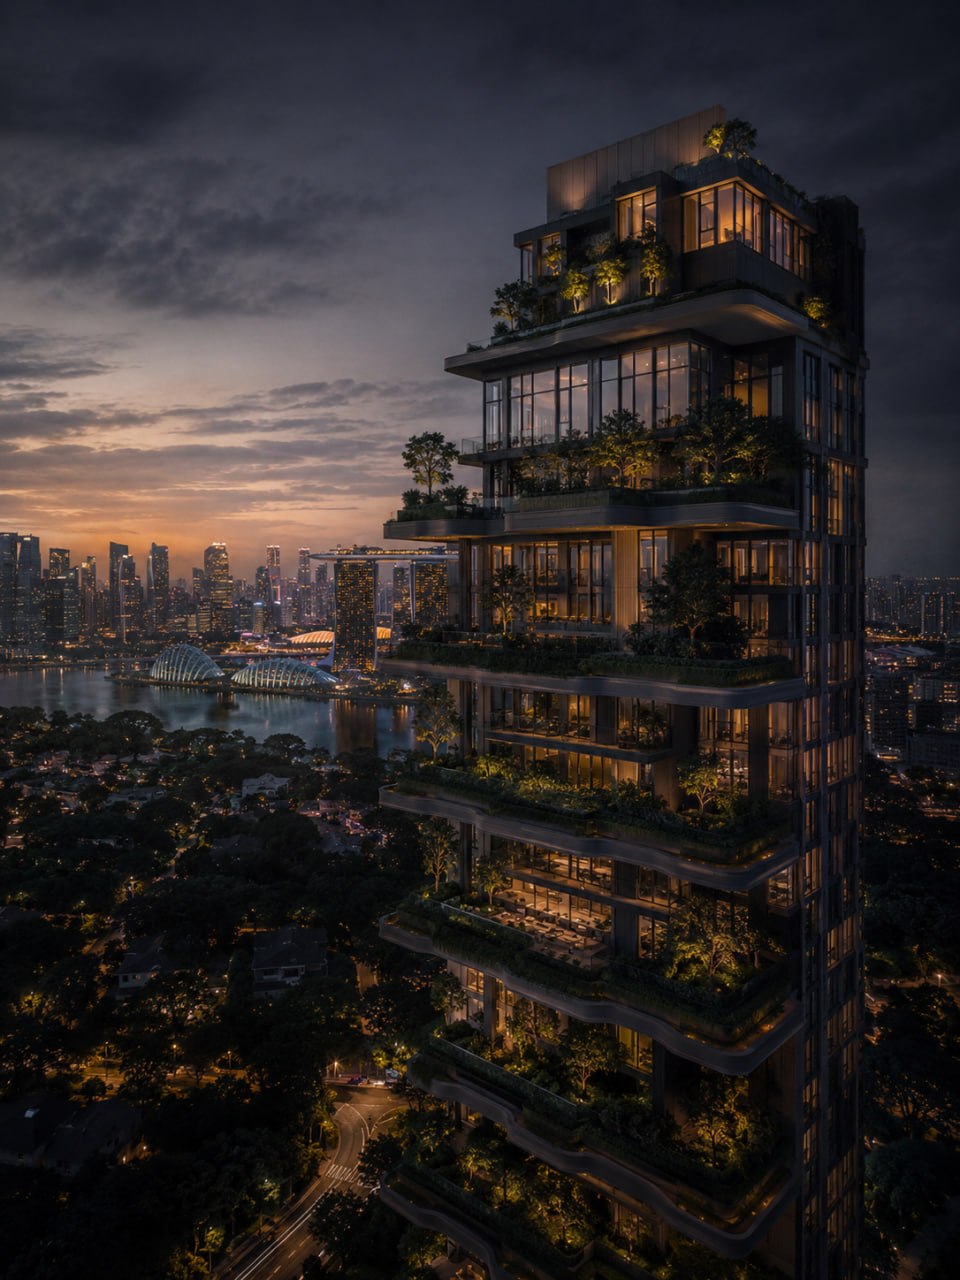
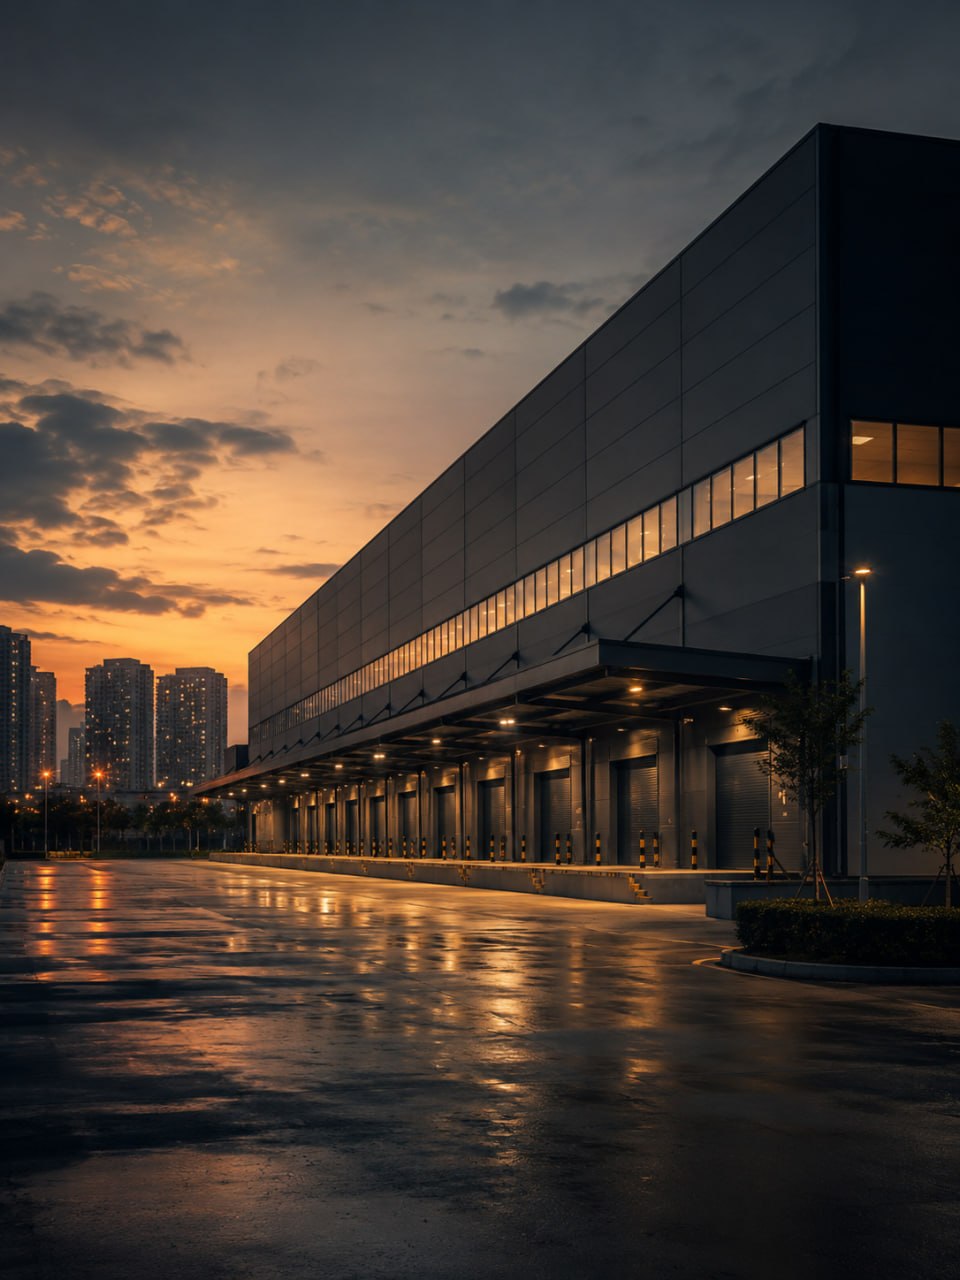
Illustrative imagery.
6.2 Underwriting Criteria
- Independent valuation from a recognized international firm (JLL, CBRE, Knight Frank, Cushman & Wakefield, or equivalent)
- Minimum three-year track record of occupancy and rental income (or credible feasibility for development assets)
- Technical due diligence covering structural condition, environmental profile, and capex requirements
- Title clearance and confirmation of absence of material encumbrances
- Tenant concentration assessment: no single tenant to represent more than 40% of gross income in a stabilized asset
- Jurisdictional legal opinion on enforceability of SPV structure and investor rights